Annuity Lead ROI: What 100 FIA Leads Should Really Earn You
Most agents judge leads by price. The better question is: for every dollar I put in, how much comes back? Fixed indexed annuity (FIA) leads can look expensive next to a quick final-expense list — but because a single annuity case pays a large commission, the ROI math works very differently. Here's a simple framework and a worked example.
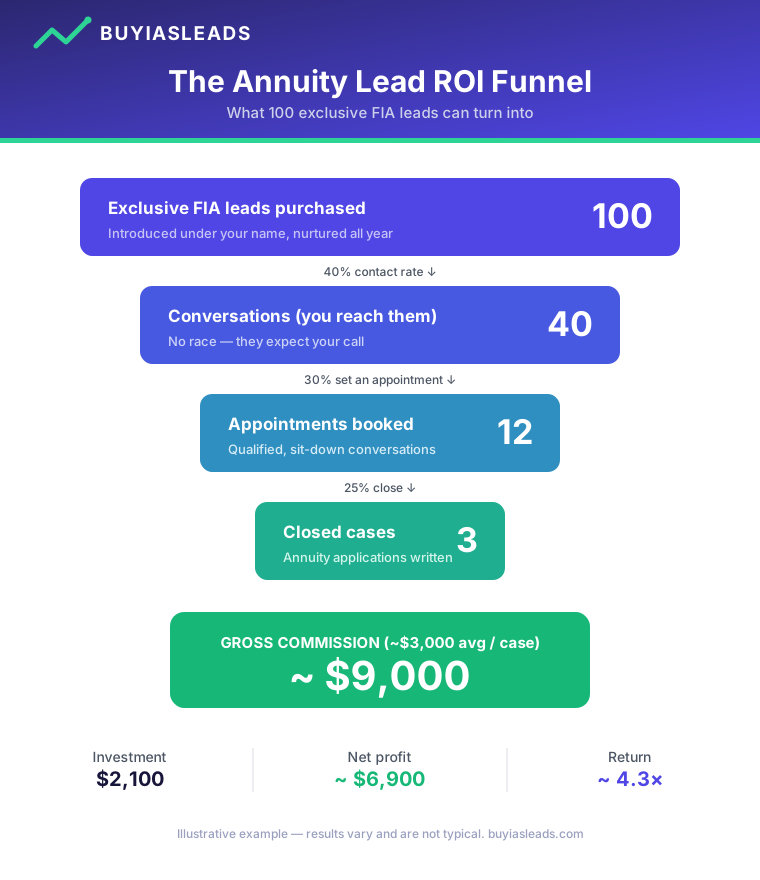
The only formula you need
Sales × average commission − lead cost = profit.
Four conversion steps, one commission number, minus what you paid. That's it. The leverage in annuities is the commission: one good FIA case can be worth thousands, so you don't need a high close rate for the numbers to work — you need to actually reach and sit with people.
A worked example: 100 exclusive FIA leads
Say you buy a 100-lead package for $2,000 (plus a $100 CRM seat). Use conservative numbers — the point is the shape of the math, not a promise:
| Step | Rate | Result |
|---|---|---|
| Exclusive leads purchased | — | 100 |
| You reach them (contact rate) | 40% | 40 conversations |
| Set an appointment | 30% | 12 appointments |
| Close a case | 25% | 3 cases |
| Avg. FIA commission per case | — | ~$3,000 |
| Gross commission | — | ~$9,000 |
| Lead + CRM cost | — | −$2,100 |
| Net | — | ~$6,900 |
Even if only one case closed, you'd be roughly at break-even to modestly profitable — and most agents don't stop at one. That's the asymmetry of annuity leads: your downside is capped at the lead cost, while a single larger case (a $500k rollover, say) can return many times the entire package.
Why exclusivity and nurture move these numbers
Every rate in that table is driven by whether you can reach people. Shared leads tank your contact rate (the prospect's been called five times already). Exclusive leads that are introduced under your name and nurtured all year do the opposite — they lift contact and appointment rates, which is where the ROI is actually won. A 40% contact rate instead of 15% roughly doubles everything downstream.
How to know your own ROI
- Track four numbers per batch: dials/contacts, appointments, closes, commission.
- Divide total commission by total lead spend. Above 2–3x is healthy; below 1x, fix your contact rate before buying more.
- Give a batch a fair runway — annuity cases often close weeks after the first call, which is exactly why a year-long nurture matters.
Bottom line
Annuity lead ROI isn't about buying the cheapest lead — it's about buying leads you can reach and sit with, then letting the commission math do the heavy lifting. Price the program on expected profit, not on cost per lead.
Run the math on your own numbers
Book 15 minutes with Gregory and we'll sketch the ROI for your market and close rate.
Book a call →